⚜️ Flood Insurance in South Louisiana: NFIP vs. Private Flood Insurance ⚜️IntroductionIf you've spent any time buying, selling, or owning a home in South Louisiana, you've probably heard the
Dated: July 3 2026
Views: 29
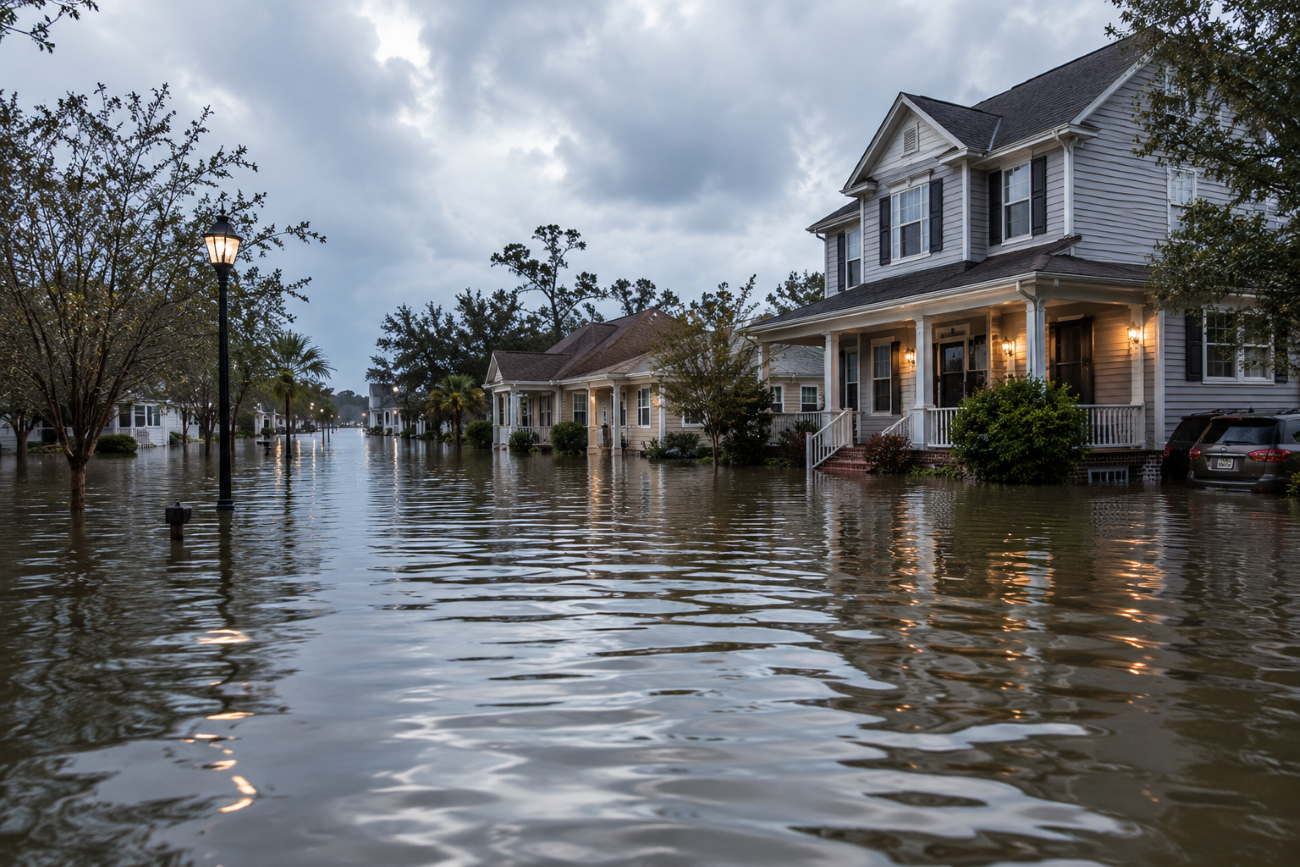
If you've spent any time buying, selling, or owning a home in South Louisiana, you've probably heard the words "flood insurance" more times than you can count.
As a REALTOR® serving Greater New Orleans and the Northshore, flood insurance is one of the most common topics that comes up during a transaction. Buyers want to know if flood insurance is required, sellers want to know what information they should provide, and homeowners often wonder if there are ways to reduce their costs.
One thing I've learned over the years is that flood insurance isn't just an insurance conversation. It's a real estate conversation.
Why?
Flood insurance can directly affect affordability, monthly payments, purchasing power, and even whether a buyer decides to move forward with a home.
Recently, I was working with a first-time homebuyer who found a home he loved in Slidell. The home checked nearly every box on his wish list and seemed to fit comfortably within his budget.
Then we received the flood insurance quote.
The National Flood Insurance Program (NFIP) premium came back at approximately $3,800 per year, adding more than $320 per month to his housing payment.
Knowing how much that could affect affordability, I contacted a private flood insurance company to see if a lower-cost alternative was available. Unfortunately, the private carrier declined to insure the property altogether.
Suddenly, the true monthly cost of owning that home looked very different from what it did on paper.
I've experienced the other side of the equation personally.
Several years ago, my own NFIP flood insurance premium nearly tripled. Rather than simply accepting the increase, I started shopping for alternatives and found a private flood insurance policy that saved me more than $1,000 per year while still providing the coverage I needed.
Those two experiences taught me an important lesson:
Flood insurance matters, and understanding your options can make a significant difference when buying or owning a home in South Louisiana.
When buyers begin searching for homes, most focus on:
• Purchase price
• Interest rate
• Property taxes
• Homeowners insurance
What sometimes gets overlooked is flood insurance.
Yet flood insurance can have a major impact on a buyer's monthly payment.
Two homes may have similar purchase prices but dramatically different ownership costs depending on their flood insurance requirements.
Home A
• Mortgage Payment: $2,000/month
• Flood Insurance: $50/month
Total Housing Cost: $2,050/month
Home B
• Mortgage Payment: $2,000/month
• Flood Insurance: $320/month
Total Housing Cost: $2,320/month
Even though the homes may have identical sale prices, the monthly cost difference can significantly affect affordability.
That's why I encourage buyers to investigate flood insurance costs early in the home search process rather than waiting until the final stages of a transaction.
One of the first questions buyers ask is:
"Is this property in a flood zone?"
The reality is that every property is located within a FEMA flood zone designation.
Common flood zones throughout Southeast Louisiana include:
• Flood Zone X
• Flood Zone AE
• Flood Zone VE
• Flood Zone A
While properties in certain flood zones may require flood insurance as part of the mortgage process, flood risk exists in many areas regardless of flood zone designation.
Understanding a property's flood zone is simply one piece of the overall picture.
Many homeowners are surprised to learn that there may be more than one flood insurance option available.
The NFIP is administered through FEMA and has long been the primary source of flood insurance coverage throughout the country.
Many South Louisiana homeowners currently carry NFIP policies.
Over the last several years, more private flood insurance options have entered the market.
Depending on the property, some homeowners may discover:
• Lower premiums
• Different coverage options
• Additional flexibility
However, not every property qualifies for private flood insurance.
As my Slidell buyer discovered, some homes may only qualify for NFIP coverage.
Every property is different, which is why obtaining quotes early can be so important.
Questions Buyers Should Ask Before Making an Offer
When considering a property, buyers should ask:
✔ What flood zone is the property located in?
✔ Is flood insurance required by the lender?
✔ What is the current annual flood insurance premium?
✔ Has the property experienced previous flooding?
✔ Is an elevation certificate available?
✔ Are there private flood insurance options available?
✔ Can the current flood insurance policy be assumed by a new owner?
One question many buyers don't realize they can ask is whether the seller's existing flood insurance policy may be transferable.
In some situations, an existing flood insurance policy can be assigned to a new owner if eligibility requirements are met and the insurance provider approves the transfer.
This can be especially valuable when the seller has an older policy with favorable rates or when current premiums are significantly higher than they were when the policy was originally issued.
While transferability is never guaranteed, it's worth investigating early in the transaction, particularly when flood insurance represents a significant portion of the monthly housing expense.
Buyers should always verify eligibility, transfer requirements, and any potential changes in premium directly with the insurance provider.
Understanding these answers before making a purchasing decision can help buyers avoid surprises later.
Flood insurance isn't only important to buyers.
Today's buyers are increasingly educated and often ask questions about:
• Current flood insurance costs
• Flood zone designations
• Previous flood claims
• Elevation certificates
Having this information readily available can help create smoother conversations during the transaction process and reduce last-minute surprises.
Transparency often helps buyers feel more confident when evaluating a property.
Sellers may also want to have information about their current flood insurance policy readily available, including the current premium and whether the policy may be eligible for transfer to a new owner. Having this information available can help answer buyer questions early in the process.
I'm not an insurance agent, and I always encourage buyers and sellers to consult licensed insurance professionals regarding coverage options and policy recommendations.
However, as a REALTOR®, I've seen firsthand how flood insurance can impact real estate decisions.
My recommendation is simple:
Don't wait until the final days before closing to investigate flood insurance.
Understand the costs early.
Ask questions.
Explore available options.
And make sure you're evaluating the total monthly cost of homeownership, not just the purchase price.
Flood insurance is simply part of life in much of South Louisiana.
While it can sometimes feel overwhelming, understanding how flood insurance affects affordability can help buyers and homeowners make more informed decisions.
My own experience finding a lower-cost private flood policy showed me that alternatives may exist.
My buyer's experience in Slidell reminded me that every property is unique and not every solution works for every home.
The key is understanding the property, researching your options, and gathering information early in the process.
If you're considering buying or selling a home in Greater New Orleans or on the Northshore and have questions about flood zones, flood insurance considerations, or how these factors may impact your real estate goals, I'd be happy to help guide you through the process.
Is flood insurance required on every home in South Louisiana?
No. Flood insurance requirements typically depend on the property's flood zone designation and lender requirements.
Absolutely. Flood insurance premiums can vary significantly from one property to another.
It may be worth exploring available options and discussing coverage with licensed insurance professionals.
No. Flooding can occur in many areas, including properties located outside higher-risk flood zones.
Can a flood insurance policy be transferred to a new owner?
In some cases, yes. Certain flood insurance policies may be eligible for transfer if the insurance provider's requirements are met. Buyers should verify transferability and any potential premium changes directly with the insurance provider before closing.
• Understanding Flood Zones in South Louisiana
• Hurricane Preparation in South Louisiana: A Step-by-Step Timeline Before the Storm Arrives
• Free Printable South Louisiana Hurricane Preparation Checklist
#PatriciaSellsNOLA #REMAXAlliance #abovethecrowd
#FloodInsurance #NFIP #PrivateFloodInsurance
#SouthLouisianaRealEstate #NewOrleansRealEstate
#NorthshoreRealEstate
With over a decade of experience in the real estate industry, Patricia Conaghan is your trusted partner in navigating the vibrant and diverse markets of Greater New Orleans. Recognized as a Top 500 Me....
⚜️ Flood Insurance in South Louisiana: NFIP vs. Private Flood Insurance ⚜️IntroductionIf you've spent any time buying, selling, or owning a home in South Louisiana, you've probably heard the
📥 Tip: To print this checklist, click Ctrl+P (Windows) or Command+P (Mac) and print this page. You can also save it as a PDF for future hurricane seasons. Or right-click on the flyer
⚜️ Hurricane Preparation in South Louisiana: A Step-by-Step Timeline Before the Storm Arrives ⚜️IntroductionLiving in South Louisiana comes with many advantages: incredible food, unique
⚜️ Is Today's Housing Market Like the 1980s? Here's My Take as a Louisiana Realtor ⚜️IntroductionOne of the questions I hear from both buyers and sellers is:"Have we ever seen a housing
 The multiple listing information is provided by the Greater Baton Rouge Association of REALTORS®, Inc. multiple listing service from a copyrighted compilation of listings. The compilation of listings and each individual listing are ©2026 MLS. All Rights Reserved. The information provided is for clients' personal, non-commercial use and may not be used for any purpose other than to identify prospective properties clients may be interested in purchasing. All properties are subject to prior sale
or withdrawal.
Show More...
 Copyright © 2026 New Orleans Metropolitan Association of REALTORS®, Inc. All Rights Reserved. The sharing of MLS database, or any portion thereof, with any unauthorized third party is strictly prohibited. Information contained on this site is believed to be reliable; yet, users of this web site are responsible for checking the accuracy, completeness, currency, or suitability of all information. Neither the New Orleans Metropolitan Association of REALTORS®, Inc. nor the Gulf South Real
Estate Information Network, Inc. makes any representation, guarantees, or warranties as to the accuracy, completeness, currency, or suitability of the information provided. They specifically disclaim any and all liability for all claims or damages that may result from providing information to be used on the web site, or the information which it contains, including any websites maintained by third parties, which may be linked to this web site. The information being provided is for the consumers personal, non-commercial use, and may not be used for any purpose other than to identify prospective properties which consumers may be interested in purchasing. The user of this site is granted permission to copy a reasonable and limited number of copies to be used in satisfying the purposes identified in the preceding sentence. Last Updated: September 25, 2026 9:19 AM UTC
Show More...
 MLS United® - All information deemed reliable but not guaranteed. All properties are subject to prior sale, change, or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than REMAX Alliance may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 25, 2026 8:47 AM UTC
Show More...
